Key Takeaways
Medical coverage products can differ substantially in their purpose, covered services, payment structure, exclusions, and consumer protections.
A low monthly premium does not necessarily mean that a plan will have the lowest overall cost. Deductibles, copayments, coinsurance, benefit limits, and excluded services must also be considered.
Preventive services, mental health care, prescriptions, telehealth, dental care, and vision care are not included in every product. Consumers should confirm each benefit in the applicable policy documents.
Provider networks and prescription formularies can affect access to care and out-of-pocket expenses. Participation should be verified directly before receiving services.
Fixed-indemnity, accident, critical illness, and other supplemental products do not function in the same way as comprehensive major medical insurance.
Coverage changes may be restricted by enrollment periods, qualifying life events, underwriting requirements, or the terms of the particular product.
The policy or certificate controls the coverage. Marketing materials, summaries, and conversations with agents can be helpful, but they should not replace a careful review of the governing documents.
Understanding What a Medical Coverage Plan Includes
Begin With the Type of Coverage
The phrase “medical coverage” can refer to several different products. These may include comprehensive major medical insurance, short-term coverage, fixed-indemnity insurance, accident coverage, specified-disease policies, or supplemental benefits.
These products do not provide identical protection. A comprehensive major medical plan generally pays eligible healthcare expenses according to its deductible, copayment, coinsurance, network, and out-of-pocket provisions. A fixed-indemnity policy typically pays predetermined amounts for covered events or services, regardless of whether those payments cover the full medical bill.
Accident and specified-disease policies have narrower purposes. They may provide benefits following a covered injury or diagnosis, but they are not automatically substitutes for comprehensive health insurance.
Consumers should identify the product category before comparing prices or benefits. Important questions include:
- Is the product comprehensive medical insurance or supplemental coverage?
- Does it cover preexisting conditions?
- Are there annual or lifetime benefit limits?
- Which medical services are excluded?
- Does the policy use a provider network?
- Does the plan satisfy the consumer’s reason for obtaining coverage?
The name of a product does not explain the full extent of its protection. The policy terms do.
Look Beyond the Premium
The monthly premium is one part of the cost of coverage. Depending on the product, an enrollee may also be responsible for deductibles, copayments, coinsurance, noncovered services, charges above a stated benefit, or care received outside a network.
A plan with a relatively low premium could result in higher costs when medical care is needed. A plan with a higher premium might provide broader benefits or lower cost sharing, but that should never be assumed without reviewing its terms.
When comparing comprehensive plans, consumers may want to examine:
- The annual deductible
- Copayments for office visits and prescriptions
- Coinsurance percentages
- The in-network out-of-pocket maximum
- Rules for care received outside the network
- Prescription drug coverage
- Prior-authorization requirements
Supplemental and fixed-indemnity products require a different evaluation. Consumers should determine how benefits are calculated, whether payments are made to the insured or provider, and how the stated amount compares with the potential medical bill.
Reviewing Costs and Access to Care
How Preventive Services May Be Covered
Preventive care can include wellness visits, vaccinations, screenings, and counseling services. However, coverage depends on the type of plan, the specific service, the patient’s eligibility, and whether an appropriate participating provider is used.
Certain comprehensive plans may cover qualifying preventive services without cost sharing when applicable requirements are met. That does not mean every diagnostic test, follow-up service, or related procedure will be free.
For example, a screening service may be covered differently if symptoms are already present or if the visit results in additional diagnostic care. Coding and billing circumstances can also affect how a claim is processed.
Before scheduling a service, an enrollee can ask:
- Is the service considered preventive under this plan?
- Are age, frequency, or risk-based requirements involved?
- Must the provider or facility be in the network?
- Is prior authorization required?
- Could laboratory work or follow-up testing result in separate charges?
Preventive care may support earlier identification of certain health concerns, but no plan can guarantee improved health outcomes or lower future expenses.
Networks, Formularies, and Additional Programs
A provider network is a group of physicians, hospitals, laboratories, pharmacies, and other healthcare organizations that have arrangements with a plan. Using a participating provider may reduce costs under some policies.
A large network does not guarantee that a particular physician or facility participates. Online directories can become outdated, and a medical office may accept some products from an insurer but not others. Consumers should verify participation with both the plan and the provider before receiving nonemergency care.
Prescription coverage deserves similar attention. A formulary identifies medications covered by the plan and may organize them into cost-sharing tiers. It can also contain requirements such as prior authorization, quantity limits, or step therapy.
Dental discounts, vision services, telehealth access, wellness programs, and pharmacy savings may be available with certain products. However, these features should not be assumed to be insurance benefits. A discount program lowers an agreed price but does not necessarily pay a claim.
Consumers should ask whether an advertised feature is:
- An insured benefit
- A discount arrangement
- A membership service
- An optional rider
- A separate policy with its own premium
- Limited to participating providers
Matching Coverage to Personal Circumstances
Enrollment Rules and Life Changes
Marriage, divorce, the birth or adoption of a child, relocation, loss of qualifying coverage, and changes in employment can affect a household’s insurance needs. They do not necessarily allow every policy to be changed immediately.
Comprehensive individual-market coverage generally follows established enrollment rules. Certain life events may create a special enrollment opportunity, subject to eligibility requirements and documentation.
Employer-sponsored coverage follows the employer plan’s enrollment procedures. Supplemental, short-term, and medically underwritten products may have different application, eligibility, renewal, or termination provisions.
Adding a dependent or changing a benefit can also affect premiums and effective dates. Consumers should contact the applicable insurer, employer, marketplace, or licensed agent promptly after a life change.
Coverage should be reviewed when circumstances change, but a change in circumstances does not guarantee that every option will be immediately available.
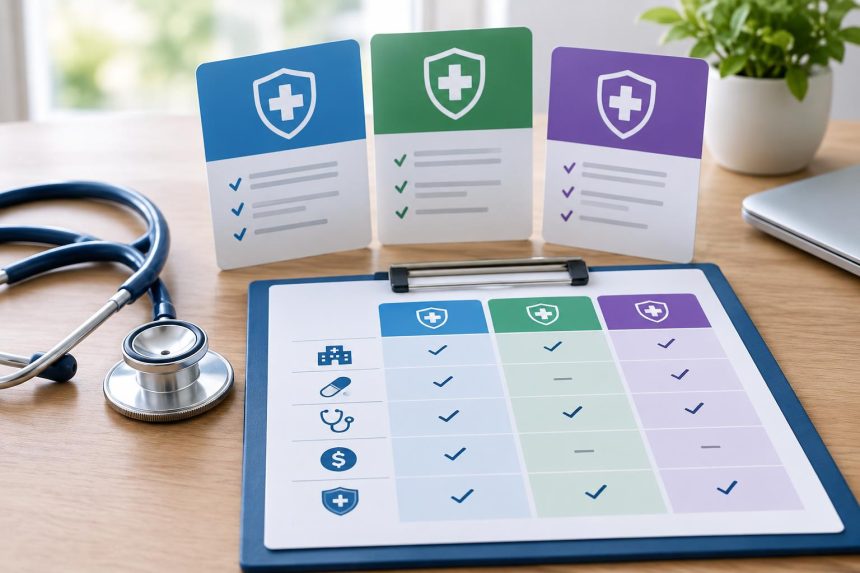
Comparing Plans With the Same Checklist
It is difficult to compare coverage accurately when one plan is evaluated primarily by its premium and another by its list of benefits. Using the same checklist for every option creates a more meaningful comparison.
People examining medical coverage plans can review information about products associated with USHEALTH Group, but availability, eligibility, benefits, and exclusions can vary by product and state. The applicable policy or certificate should be reviewed before enrollment.
A comparison checklist may include:
- Product type
- Monthly premium
- Deductible and cost-sharing requirements
- Maximum benefit amounts
- Out-of-pocket protections, if applicable
- Provider-network rules
- Prescription coverage
- Preventive and diagnostic services
- Mental health and substance-use services
- Maternity and newborn care
- Emergency and hospitalization benefits
- Preexisting-condition provisions
- Exclusions and waiting periods
- Renewal and termination conditions
- Appeals and complaint procedures
Consumers should compare plans based on their actual healthcare use. Someone who takes several prescriptions may prioritize the formulary and pharmacy network. A person receiving continuing specialist care may focus on provider participation and referral requirements.
No checklist can predict every future medical need, but a consistent review can expose important differences before enrollment.
Using Coverage With Fewer Surprises
Confirm Benefits Before Receiving Care
Possessing an insurance card does not guarantee that every service will be covered. A claim can be affected by medical-necessity requirements, exclusions, benefit limits, network status, prior authorization, or incomplete documentation.
Before receiving scheduled care, consumers can ask the insurer:
- Is the service covered under the policy?
- Is the provider participating in the specific network?
- Is the facility also in the network?
- Is prior authorization required?
- What deductible, copayment, or coinsurance may apply?
- Is there a stated maximum payment for the service?
The provider can also be asked for an estimate, although an estimate is not a guarantee of the final amount. Additional professionals involved in the service, such as laboratories, anesthesiologists, radiologists, or pathologists, may submit separate bills.
Emergency care may not allow time for advance verification. For planned care, confirming the details can reduce avoidable misunderstandings.
Keep Documents and Review Changes
Coverage documents should be retained in an accessible place. These may include the application, policy or certificate, summary of benefits, identification card, provider directory information, explanation-of-benefits statements, authorization records, bills, and correspondence.
An explanation of benefits is generally not a bill. It describes how a claim was processed, what the provider charged, what the plan paid, and what amount may be assigned to the enrollee. It should be compared with the provider’s bill.
If a claim is denied, the explanation should identify the reason and provide information about available review or appeal procedures. Deadlines may apply, so disputed claims should not be set aside indefinitely.
Policy terms, premiums, networks, formularies, and participating providers may change. Renewal materials should therefore be reviewed even when a person intends to keep the same coverage.
Understanding a plan is an ongoing responsibility, not a task that ends when enrollment is completed.
FAQ
What should consumers examine when selecting medical coverage?
Consumers should identify the product type and review its premiums, covered services, exclusions, benefit limits, cost-sharing terms, provider network, prescription provisions, and renewal conditions. Personal healthcare needs and expected use should also be considered.
Do all plans cover preventive care without cost sharing?
No. Coverage depends on the product and applicable requirements. Some comprehensive plans cover qualifying preventive services without cost sharing when network and eligibility rules are satisfied. Supplemental, fixed-indemnity, and limited-benefit products may operate differently.
Can coverage be changed whenever personal needs change?
Not necessarily. Changes may be limited to an open-enrollment period or require a qualifying life event. Other products can have separate underwriting, application, renewal, or effective-date rules.
Is mental health treatment included in every medical plan?
No. Mental health and substance-use benefits vary according to the kind of coverage and the policy. Consumers should confirm covered services, network providers, visit limits, authorization rules, and cost-sharing obligations.
Does a broad provider network guarantee access to a preferred doctor?
No. Network participation may differ by plan and can change. Consumers should verify the specific doctor and facility with the insurer and healthcare provider before scheduling nonemergency care.
Are telehealth visits always less expensive than office visits?
No. Telehealth costs depend on the plan, provider, service, and applicable cost-sharing requirements. Some plans include telehealth benefits, while others may limit the available providers or types of care.
What is the difference between insurance and a medical discount program?
Insurance pays benefits according to the terms of a policy. A discount program generally provides access to negotiated prices but does not insure the medical expense or guarantee payment toward a bill.
Which document determines what a plan actually covers?
The policy or certificate is the governing document. Summaries, brochures, directories, and agent explanations can help consumers understand the product, but the policy controls when there is a discrepancy.
Lynn Martelli is an editor at Readability. She received her MFA in Creative Writing from Antioch University and has worked as an editor for over 10 years. Lynn has edited a wide variety of books, including fiction, non-fiction, memoirs, and more. In her free time, Lynn enjoys reading, writing, and spending time with her family and friends.